Open Enrolment is on. December 15 is the last day for a January 1 start.See the dates

Mon to Thu, 8:30 am to 6:00 pm · Se habla español

Chattanooga, Tennessee

Health coverage,Neighbours talking through coverage options togetherexplained in plain words.

Independent advice for 1099 earners and families. Short sentences, no jargon, and the same premium whether you use us or not.

  • Independent, multi-carrier
  • $0 to work with us
  • No high-pressure scripts
  • English and Español

Start here

Four people ask us four completely different questions

Pick the line that sounds like your life.

Scroll sideways through the four

Southline in four numbers

Small agency, long memory

  • 1,840+

    households enrolled since 2016

  • 11

    states we hold a licence in

  • $0

    what our advice costs you

  • 4.9/5

    average from 312 client reviews

The panel we shop

We compare the whole panel, not one company

Twelve carriers, one advisor, no favourites.

See the panel by product line

What we place

Everything we can actually place for you

Nine lines, one advisor, and the ones we will tell you not to buy.

Renata Okonkwo working through a comparison at the Broad Street desk
CPBASEBSRCPA

Meet your advisor

Renata Okonkwo, founding advisor

ACA Marketplace, self-employed households and subsidy reconciliation.

Renata started Southline after nine years inside a carrier call centre, explaining bills that should never have been a surprise.

She handles the 1099 income forecasts and the mid-year reporting nobody else wants to do, in English or Portuguese.

  • Nine years inside a carrier call centre before this desk
  • Builds your income range, then checks it again in June and October
  • Will tell you to keep the plan you have when that is the right answer

How it works

Three steps, start to finish

No forms to print, no sales appointment, no obligation.

  1. 1

    Tell us the situation

    Four questions, about two minutes.

  2. 2

    We build the comparison

    Your doctors, your prescriptions, your county.

  3. 3

    You pick, we stay on the file

    Enrolment, ID cards and claims, at no cost.

Free tool · subsidy estimate

What would a premium tax credit actually do for you?

Two inputs, the same two the Marketplace starts from.

Include everyone you claim, even someone who does not need coverage.

Self-employed? Start from Schedule C net profit, not gross receipts.

235% of the federal poverty level

$20,440 is the guideline for a household of 2.

Silver CSR applies

Rough monthly premium tax credit

$879

applied straight to the premium, before you are billed

Benchmark silver premium
$1,015 a month
Your expected contribution
3.4% of income
Benchmark silver, after the credit
$136 a month

200% to 250% FPL. Roughly 2% to 4% of income. This is the last band where silver cost-sharing reductions apply at all.

What the federal poverty level bands actually do

Scroll the table sideways to see every column.

Expected household contribution toward the benchmark plan by federal poverty level band
BandExpected contributionWhat it means in practice
Up to 150% FPL0%Your expected contribution is effectively zero, so the benchmark silver plan can land at $0 a month.
150% to 200% FPL0% to 2%You are expected to pay from nothing up to about 2% of income. Silver plans also carry the strongest cost-sharing reductions here.
200% to 250% FPL2% to 4%Roughly 2% to 4% of income. This is the last band where silver cost-sharing reductions apply at all.
250% to 300% FPL4% to 6%Roughly 4% to 6% of income. Cost-sharing reductions have stopped, so the silver advantage disappears.
300% to 400% FPL6% to 8.5%Roughly 6% to 8.5% of income. Bronze and gold both become worth a serious look here.
Above 400% FPL8.5%Your contribution is capped at about 8.5% of income under the current enhanced rules. If those rules lapse, this band loses its credit entirely.

An estimate for planning, not a quote. HealthCare.gov sets your real credit.

How these figures are built

Free tool · metal levels

Metal level is a cost split, not a quality rating

Bronze is not the budget version of gold. Silver behaves oddly on purpose.

No subsidy

Under 30 only

Catastrophic

Below 60% actuarial value

$310a month

A high wall with three free primary care visits in front of it

Who it suits
Under 30, or holding a hardship or affordability exemption. Nobody else may buy it.
Deductible
Equal to the annual out-of-pocket maximum
Out-of-pocket max
Highest allowed
HSA
Not eligible
  • Premium tax credits cannot be applied to a catastrophic plan. The price you see is the price you pay.
  • Covers the same essential health benefits and includes three primary care visits before the deductible.
  • Almost always a worse deal than a subsidised bronze plan if you qualify for any credit at all.
Where this lands in the decision tree

Lowest premium

Bronze

About 60% actuarial value

$95a month

Cheapest monthly, most expensive if you actually need care

Who it suits
Healthy households with savings, or anyone whose credit covers most of the premium and who wants HSA eligibility.
Deductible
High, often several thousand dollars
Out-of-pocket max
At or near the annual legal maximum
HSA
Usually eligible
  • Preventive care is still covered at no cost, as on every compliant plan.
  • Most bronze plans are designed to qualify as high-deductible health plans, which makes an HSA possible.
  • If your credit already covers a silver plan's cost-sharing reductions, bronze is usually the wrong choice.
Where this lands in the decision tree

Check silver first

CSR tier

Silver

70% actuarial value, up to 94% with CSR

$160a month

The only metal level where cost-sharing reductions exist

Who it suits
Anyone under 250% of the federal poverty level. This is the single most misunderstood rule in the Marketplace.
Deductible
Moderate, and dramatically lower with CSR applied
Out-of-pocket max
Moderate, and much lower with CSR applied
HSA
Sometimes eligible
  • Cost-sharing reductions silently upgrade a silver plan's actuarial value to roughly 73%, 87% or 94% depending on your income band.
  • At 94% actuarial value a silver plan can out-cover a gold plan while costing less per month.
  • CSR attaches ONLY to silver. Buy a bronze or gold plan at the same income and you leave it on the table.
  • The benchmark plan that sets your credit is itself a silver plan, which is why silver is the reference point for everything.
Where this lands in the decision tree

Predictable costs

Gold

About 80% actuarial value

$280a month

Higher monthly, much lower when you use it

Who it suits
Households with known ongoing care: a chronic condition, a planned surgery, a pregnancy, regular specialists.
Deductible
Low
Out-of-pocket max
Low
HSA
Rarely eligible
  • In some rating areas gold prices very close to silver once the credit is applied, because of how the benchmark is set.
  • Worth checking every single year even if you have always bought bronze.
  • Gold deductibles are generally too low to qualify as a high-deductible health plan, so an HSA is usually off the table.
Where this lands in the decision tree

Which plan type

Five questions, asked in the order that matters

Premium is the fifth most useful question. Work through these in order instead.

Work through the five questions sideways

01

Is your household income under 250% of the federal poverty level?

Cost-sharing reductions attach to silver plans only, and they stop at 250%. This question outranks every other question on the page.

  • Yes, under 250%Start with silver. Your deductible and out-of-pocket maximum are quietly reduced, and below 150% the reduction is dramatic.
  • No, above 250%Silver loses its special power. Compare bronze, silver and gold on total expected cost instead.
02

Do you take a prescription that costs real money every month?

Drug tiers differ by plan, not by metal level. One specialty medication can decide the whole comparison on its own.

  • YesCheck the formulary before the premium. A plan that puts your drug on tier 4 can cost more than a richer plan that puts it on tier 2.
  • NoYou have more freedom to optimise on premium and deductible. Still check that nothing new is on the horizon.
03

Do you expect to use care this year beyond a checkup?

Metal level is a cost-sharing split, not a quality rating. The question is where you want the money to land.

  • Probably notBronze, or subsidised silver if you are under 250%. Preventive care is free on every compliant plan.
  • Yes, a surgery, a birth or a chronic conditionGold, or silver with cost-sharing reductions. Paying more monthly buys a much smaller worst case.
04

Do you want a Health Savings Account?

HSA eligibility is a property of the specific plan, not of the metal level. It requires a qualifying high-deductible health plan.

  • YesFilter to plans marked HSA-eligible. Most are bronze, some are silver, gold almost never qualifies.
  • NoIgnore the HSA label entirely and optimise on network, drug list and total expected cost.
05

Are you under 30, or do you hold a hardship exemption?

Catastrophic plans are restricted, and no premium tax credit can be applied to them.

  • Yes, and I get no subsidyA catastrophic plan is worth pricing. It covers the same essential benefits with three pre-deductible primary care visits.
  • Yes, but I do qualify for a creditSkip catastrophic. A subsidised bronze or silver plan will almost always beat it.

When your income moves

Your income changed in July. Now what?

Five steps, in plain words, ending at Form 8962.

Follow the five steps sideways

01

Your income moves

A retainer ends, a contract lands, you take a W-2 job in August, or a quiet quarter turns into a busy one. For a 1099 earner this is normal, not an emergency.

The Marketplace set your advance credit from an estimate you made months ago. It does not update itself, and nobody is watching your bank account.

02

You report the change

Update your application at HealthCare.gov, ideally within 30 days. You can also call us and we will do it with you on a screen share.

Reporting a raise lowers your monthly credit now. That feels bad in September and feels very good in April. Reporting a drop raises it immediately, which is real money back in your month.

03

Your monthly credit adjusts

The advance premium tax credit is recalculated from the new estimate and applied from the next available coverage month.

Changing the estimate does not change your plan, your deductible or your doctors. It only changes how much of the premium is paid in advance on your behalf.

04

Tax time reconciles it

The Marketplace sends Form 1095-A in January. Your preparer uses it to complete Form 8962, which compares the credit you received against the credit your actual income earned.

Took too much, you repay the difference. Took too little, it comes back as a refundable credit. Repayment is capped at certain income levels, but above 400% of the federal poverty level the repayment is generally uncapped.

05

Levers you still have in December

A deductible retirement contribution lowers modified adjusted gross income, which raises the credit you were entitled to.

A SEP-IRA or solo 401(k) contribution is the classic one for self-employed households. We are not tax advisers, so we flag it and your CPA runs the numbers.

Free tool · enrolment windows

The windows are real deadlines, and they close

Miss one and you wait a year, unless something specific has happened.

36

days until Open Enrolment opens

November 1

80

days to the December 15 deadline

for a January 1 start

72

days until Medicare AEP closes

December 7

60

days is your Special Enrolment clock

from the event, not from when you noticed

Open Enrolment

November 1 to January 15

ACA Marketplace, individuals and families

Enrol by December 15 for a January 1 start

After January 15 you need a qualifying life event to enrol at all.

Medicare Annual Enrolment

October 15 to December 7

Anyone on Medicare Advantage or Part D

Changes take effect January 1

This is when we re-run your drug list against next year's plans.

Medicare Advantage Open Enrolment

January 1 to March 31

People already enrolled in a Medicare Advantage plan

One change allowed

You can switch Advantage plans or return to Original Medicare with a Part D plan.

Initial Enrolment Period

Seven months around your 65th birthday

Anyone approaching 65

Three months before, your birthday month, three months after

Enrolling in the three months before avoids a gap. Missing it can create a lifetime Part B penalty.

You get 60 days from the event, not 60 days from when you noticed

The clock runs from the date of the qualifying event itself. Miss it and the next opportunity is Open Enrolment, which can mean months uninsured. For most events you can also apply in the 60 days before a planned loss of coverage, which is the better move when you already know the end date.

  • You lost coverage

    A job ended, a plan ended, you aged off a parent's plan at 26, or COBRA ran out. Voluntarily dropping coverage does not count.

    Termination letter or a letter of creditable coverage showing the end date

  • You moved

    A permanent move to a new ZIP code or county that changes the plans available to you. You must have had coverage for one of the previous 60 days.

    Lease, deed, utility bill or USPS confirmation with the move date

  • You married

    Marriage opens a window for both spouses. At least one of you generally needs prior coverage in the previous 60 days.

    Marriage certificate

  • A baby arrived

    Birth, adoption or placement for foster care. Coverage can usually be backdated to the date of the event.

    Birth certificate, hospital record or placement papers

  • Your income changed

    A change that makes you newly eligible or newly ineligible for a premium tax credit or for cost-sharing reductions.

    Pay records, a new contract, or an updated Schedule C projection

  • You gained citizenship or lawful status

    Newly eligible immigration status or naturalisation opens a Marketplace window.

    Naturalisation certificate or immigration documentation

  • You left incarceration

    Release from detention opens a Special Enrolment Period.

    Release documentation with the date

  • A carrier error or a plan violation

    If a plan substantially violated its contract or you were enrolled in error, the Marketplace can open a window on request.

    Documentation of the error, usually gathered with us

Why Southline

Two reasons, and both are checkable

Everything else on this page follows from these.

The Southline office on Broad Street

Independent, never captive

We represent the market, not one company

A captive agent has one panel and one answer. We hold appointments across twelve carriers, so the comparison is between real alternatives. We will also tell you when a plan we cannot place is the better one for you.

  • Every on-exchange carrier in your county compared, not just the two that pay best
  • Plan availability differs by county, so we check your address rather than your city
  • We do not offer every plan available in your area, and we say so plainly
See the carrier panel
A video appointment running on a laptop at a kitchen table

Free, and we will explain why

You pay the same premium either way

Plan rates are filed with the state. Enrol on your own at midnight, call the Marketplace, or sit with us: the price is identical. Carriers pay us out of their own margin, so there is no fee and no reason to rush you.

  • No fee, no retainer, no consultation charge, at any stage
  • We are paid on the plan you choose, and we are paid on renewals, which is why bad advice is bad business
  • If the right answer is to keep what you have, that is what we will tell you
How we work

No appointment needed

Not sure your plan is still the right one?

Read us your card over the phone. It usually takes ten minutes.

(423) 555-0243

Mon to Thu, 8:30 am to 6:00 pm · TTY 711

Affiliations

Who we answer to

Membership, accreditation and the pledge that keeps our copy in plain words.

  • Guild of Independent Benefit AdvisorsMember since 2016
  • Southbridge Institute of Benefits PracticeAccredited practice
  • Larkfield Academy of Retirement CoverageFaculty affiliate
  • Tennessee Valley Small Business AllianceBusiness member
  • Plain Language Coverage PledgeSignatory
  • Hamilton County Community PartnersSeminar host

What clients say

What people say once the panic is over

Named, with the town they live in.

4.9

from 312 reviews across six service areas

Renata found the silver plan actually paid less than the bronze one I had picked myself. I did not know cost-sharing reductions existed.

Denise KowalczykNorthshore, Chattanooga · ACA Marketplace

I do framing work. Summer is good, February is not. They built the income estimate around the whole year instead of the month I walked in.

Andre BeaumontSoddy-Daisy, TN · Self-employed health

Marcus started my file six months before my birthday and explained the Medigap window. Nobody else had mentioned it.

Harriet SimmsSignal Mountain, TN · Turning 65

Alma did the whole appointment in Spanish for my mother and in English for me. The kids ended up on CoverKids, which we did not know about.

Tomás VegaEast Ridge, TN · Family coverage

Priya quoted a group plan and an ICHRA side by side and told us the group plan was wrong for our headcount. We went ICHRA.

Lindsay OkaforCleveland, TN · Group benefits

They talked me out of the plan with the best dental allowance because my cardiologist was out of network. Right call.

Ray MullinaxFort Oglethorpe, GA · Medicare Advantage

I landed a big contract in July and called them the same week. Updating the estimate then saved me a four-figure bill in April.

Bethany CruzSt. Elmo, Chattanooga · Income change reporting

Brought in five bottles. They ran every one against every plan and found the one where none of them sat on tier four.

Wendell PratherHixson, TN · Part D

Three ways to meet

Meet us wherever you will actually turn up

Same appointment either way. Only your travel time changes.

The Southline office interior on Broad StreetIn person

The Broad Street office

  • 801 Broad Street, Suite 300
  • Chattanooga, TN 37402

Today: 9:00 am - 1:00 pm (Nov 1 to Jan 15)

Metered street parking, and a lot behind the building. Bring your prescription bottles and your last tax return if you have it.

A video appointment on a laptopOnline

A video appointment

  • Screen share, anywhere in our licensed states
  • Usually 25 to 40 minutes

Today: Same-week slots, most weeks

We share the screen while we build your comparison, so you watch the decision being made instead of receiving a PDF later.

An in-home appointment at a kitchen tableIn home

Your kitchen table

  • Hamilton, Bradley and Catoosa counties
  • Evenings available for trades and shift workers

Today: Mondays, Tuesdays, Wednesdays and Thursdays

For Medicare appointments this is still the most common request, and for contractors it is the only hour that works.

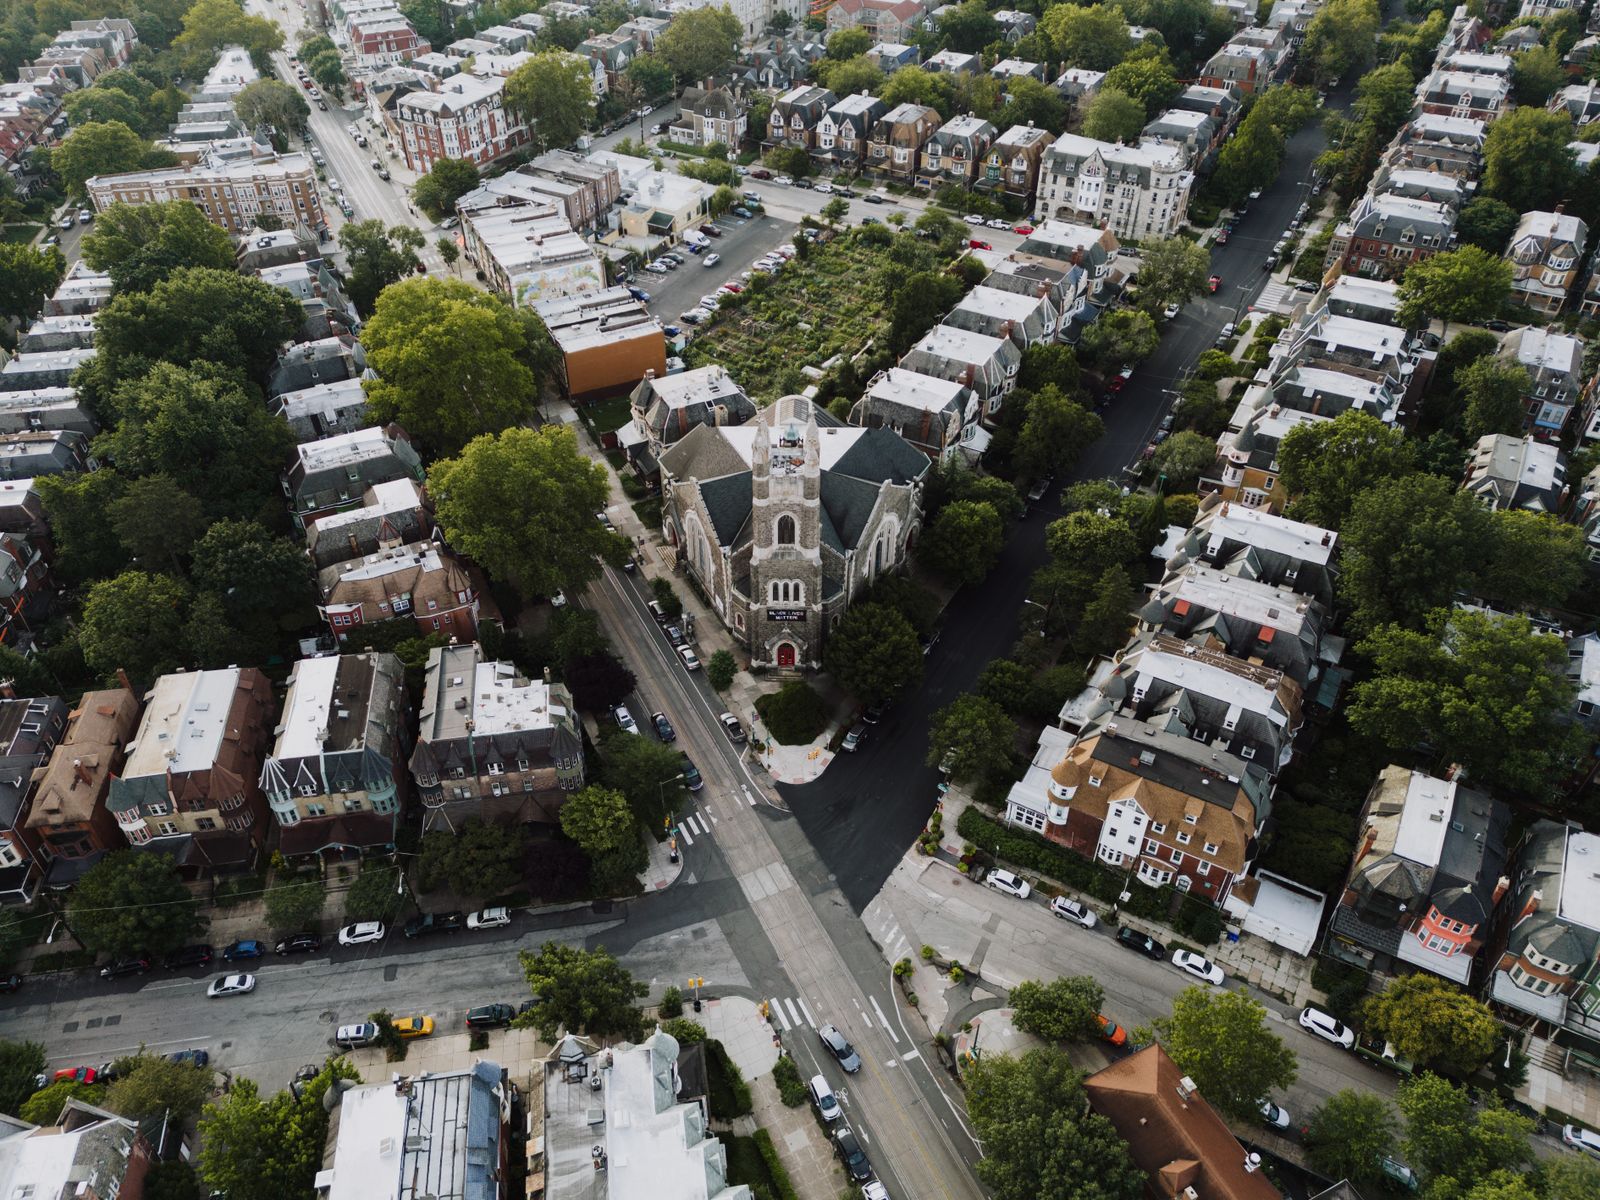
An aerial view of the neighbourhoods we coverHamilton, Bradley and Catoosa counties, plus ten more states by licence

Two states, one office

Plan availability is set by county, so we ask for the address, not the city.

Questions people ask

The six we hear every week

Short answers. The long versions live in the guides.

Every question we get asked

Nothing. There is no fee, no consultation charge and no retainer. We are compensated by the carrier whose plan you choose, and plan premiums are filed with the state, so the price is the same whether you enrol with us, over the phone with the Marketplace, or on your own at midnight.

A silent upgrade to a silver plan for households under 250% of the federal poverty level. The plan's actuarial value rises to roughly 73%, 87% or 94% depending on your income band, which means a lower deductible and a lower out-of-pocket maximum for the same premium. Buy bronze instead and you leave it behind.

Report it to the Marketplace, ideally within 30 days. Your monthly credit drops, and you avoid repaying a year's worth of excess credit on Form 8962 at tax time. Repayment is capped at some income levels; above 400% of the federal poverty level it is generally uncapped.

Only with a qualifying high-deductible health plan. Most bronze plans qualify, some silver plans do, gold almost never does. It is a property of the exact plan, so we check the plan document rather than the metal colour.

No. It runs from the date of the event itself. For a planned loss of coverage you can often apply in the 60 days before it happens, which avoids any gap at all.

If you are already receiving Social Security, usually yes for Part A and Part B. If you are not, nothing happens unless you act. That is the single most common expensive surprise we see.

Two emails a year

A reminder when a deadline is close

One before Open Enrolment, one before it closes. Nothing else, ever.

Please enter a valid email address.

Done. We will nudge you before November 1.

Start here

That is the whole process. Start it here.

An advisor picks this up within one business day. No call centre, no script.

  1. 01You tell us the situationFour questions. Household, income range, timing, and how you want to meet.
  2. 02We build the comparisonYour doctors, your prescriptions and your county, run against the panel we represent.
  3. 03You see two or three optionsWith the reasons the others are out, in writing, before anything is signed.
  4. 04We stay on the fileIncome changes, ID cards, claim questions and the autumn re-run. Still no cost to you.

Rather talk? (423) 555-0243, Monday to Thursday, 8:30 am to 6:00 pm. TTY 711.

Our help is free to you. We are paid by the carrier you choose, and the premium is the same whether you use us or enrol on your own.

Step 1 of 4

About two minutes. No payment details, ever.

What can we help with?

Pick the closest one. We will work the rest out on the call.

Tell us about the household

A range is fine. We build the real estimate together, and you can change it later.

When do you need this to start?

Pick the option closest to your situation.

The 60-day Special Enrolment clock runs from the event, so the date matters.

Where do we reach you?

Please enter your name.

We need a number to call you back on.

Please enter a valid email address.

Prescriptions, doctors you want to keep, or a date you are counting down to.

Got it. An advisor has your request.

Here is exactly what happens next, so none of it is a mystery:

  1. 1Someone calls or texts within one business day to book a 25-minute appointment, in the format you asked for.
  2. 2Before the call, gather your prescriptions with doses, the doctors you want to keep, and a rough income number.
  3. 3On the call we build the comparison on screen with you, and we say plainly which options are out and why.
  4. 4If you enrol, we stay on the file. Income changes, ID cards and claim questions come to us, at no cost.

Cookie preferences

Choose which cookies you allow. You can change this at any time from the link in the footer.